Legal partner
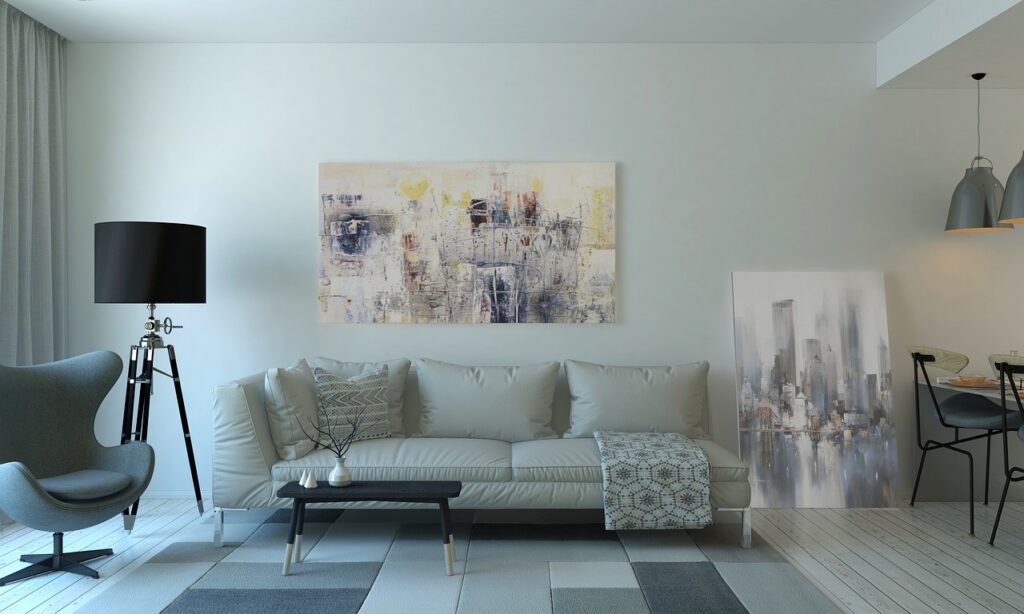
A fully furnished two-room flat in Munich, 60 square metres, advertised as “temporary living” for €1,950 a month. Unfurnished, the local comparative rent would be €1,200. How much of the difference is attributable to the sofa, the bed and the kitchen appliances can hardly be verified today – and this is exactly where the legislator steps in.
On 14 October 2026, the Legal Affairs Committee of the Bundestag will hear experts on the government bill amending the law on residential and commercial tenancies, known as Rent Law II (BT-Drs. 21/6807). The bill regulates the furniture surcharge, caps index-linked rents in tight markets, limits short-term leases and extends the grace-period payment to ordinary termination. For property valuation this is more than tenancy law: each of these rules changes which rent is legally achievable – and with it the income on which rental value appraisals and the income value are based.
The key point
A furniture surcharge is to be reasonable only if it does not exceed 1 per cent of the estimated current value of the furnishings per month; for fully furnished accommodation, up to 10 per cent of the unfurnished rent is presumed reasonable. In designated areas, index-linked rents will follow the index above 3 per cent a year only by half. For appraisal reports this means: what counts is the permissible income, not the advertised one – and the current value of the furniture becomes a valuation issue.
Where the legislative procedure stands
Rent Law II is the second part of the Federal Government's tenancy law package. The first part is already in force: the rent cap (Mietpreisbremse) has been extended until 31 December 2029. In Bavaria it applies, under the Tenant Protection Ordinance as revised with effect from 1 January 2026, in 285 towns and municipalities, including Munich.
| Date | Procedural step |
|---|---|
| 29.04,2026 | Federal Cabinet decision |
| 12.06,2026 | Opinion of the Bundesrat (BR-Drs. 265/26) |
| 01.07,2026 | Government bill introduced in the Bundestag (BT-Drs. 21/6807) |
| July 2026 | First reading, referral to the Committee on Legal Affairs and Consumer Protection |
| 14.10,2026 | Public hearing in the Legal Affairs Committee |
Nothing has been adopted yet; the bill may still change in committee. Under Article 3 of the bill, the rules on short-term leases, the furniture surcharge and the duty to provide information are to enter into force on the first day of the fourth calendar month following promulgation, everything else on the day after promulgation. For leases concluded before entry into force, Sections 549, 556d and 556g BGB continue to apply in their current version (Article 2 of the bill).
Furniture surcharge: the current value becomes a valuation issue
To date, the law does not say how a furniture surcharge is to be calculated. The courts work with different models; the explanatory memorandum mentions the “Berlin” and the “Hamburg model”, both of which start from the purchase value and the age of the furniture. Because the surcharge is rarely shown separately in practice, it is hardly possible to check whether the rent cap is complied with for furnished flats.
The bill therefore inserts into Section 556d BGB a new subsection 1a. Under it, the local comparative rent for furnished accommodation is increased by a reasonable furniture surcharge. The bill defines what is reasonable as follows:
“The furniture surcharge is reasonable if it does not exceed, per month, 1 per cent of the current value of the furnishings, as can be determined by estimation, at the time the contract is concluded.”
Section 556d(1a) BGB-E, BT-Drs. 21/6807
Three further rules are decisive in practice:
- Presumption for full furnishing: For fully equipped accommodation, a surcharge of up to 10 per cent of the rent for the unfurnished flat is presumed to be reasonable. The presumption is rebuttable (Section 292 ZPO): if the tenant proves that 1 per cent of the current value is lower, the lower amount applies.
- Rent index: If an applicable qualified rent index already takes the furnishings into account – a fitted kitchen, for example – no surcharge is payable to that extent.
- Duty to provide information: The landlord must disclose the amount of the surcharge, unprompted, before the tenant makes the contractual declaration (Section 556g(1b) BGB-E). If this is not done, the flat is deemed let unfurnished for the purposes of the permissible rent – for two more years after the information has been provided later.
In a dispute, according to the explanatory memorandum, the landlord must supply the underlying facts, such as invoices or market prices; the court may then use Section 287 ZPO to estimate the current value. Worn-out, worthless furniture generally does not justify a surcharge.
How the current value can be estimated
The bill does not prescribe a method. What is meant is the value the furnishings still have when the contract is concluded – not the purchase price. In valuation practice it is derived from the purchase or replacement value and reduced by the loss in value due to age and wear; second-hand market prices serve as a plausibility check. Useful lives from the tax depreciation tables are an indication, but not a yardstick for the market value of used furniture.
The estimate only becomes robust with an inventory: item, year of purchase, purchase price with receipt, condition, assumed useful life and current value. For the example flat, in simplified form:
| Position | Approach |
|---|---|
| Furnishings excluding fitted kitchen (assumption: already covered by the qualified rent index), purchased in 2023 | 18,000 € |
| Assumed useful life, straight-line loss in value | 10 years |
| Age when the contract is concluded in 2027 | 4 years |
| Current value at conclusion of the contract (60 per cent) | 10,800 € |
| Maximum surcharge based on current value (1 per cent per month) | €108 per month |
| Presumed reasonable for full furnishing (10 per cent of €1,200) | €120 per month |
Here the flat rate exceeds the current-value approach. If the tenant rebuts the presumption with their own estimate of the current value, the surcharge stays at €108 – and a landlord without receipts has little to counter it with.
What this means for the permissible rent
In areas with a rent cap, the rent at the start of the tenancy may exceed the local comparative rent by no more than 10 per cent (Section 556d(1) BGB). According to the wording of the bill, the reasonable furniture surcharge already increases the comparative rent to which these 10 per cent refer. For the example flat this gives:
| Position | Amount |
|---|---|
| Local comparative rent, unfurnished (60 m² × €20/m², assumption) | 1,200 € |
| + Furniture surcharge (presumed reasonable) | 120 € |
| = Comparative rent, furnished | 1,320 € |
| Maximum rent at the start of the tenancy (+ 10 per cent) | 1,452 € |
| Asking rent “temporary living” | 1,950 € |
| Difference per month / per year | 498 € / 5,976 € |
The exemptions from the rent cap remain unaffected: it does not apply to flats used and let for the first time after 1 October 2014, nor to the first letting after comprehensive modernisation (Section 556f BGB); a higher previous rent may still be charged (Section 556e BGB). Where the agreed rent exceeds the permissible rent, the agreement is invalid; under Section 556g BGB the tenant can reclaim rent paid in excess.
Index-linked rent: cap above 3 per cent
With an index-linked rent, the rent follows the consumer price index. It must remain unchanged for at least one year at a time, and an increase to the comparative rent under Section 558 BGB is excluded (Section 557b BGB). Under the new Section 557b(4) BGB-E, half of the part by which the index exceeds 3 per cent within one year is disregarded in the adjustment. The cap only applies in municipalities that a state government specifically designates for this purpose by ordinance, in each case for no more than five years. It covers adjustment declarations received after the area has been designated.
| Index increase within one year | Permissible adjustment | Example: €1,500 net rent |
|---|---|---|
| 2,0 % | 2,0 % | + 30,00 € |
| 3,3 % | 3,15 % | + €47.25 instead of €49.50 |
| 5,0 % | 4,0 % | + €60.00 instead of €75.00 |
| 8,0 % | 5,5 % | + €82.50 instead of €120.00 |
At 3.3 per cent – the inflation rate in September 2026 according to the provisional estimate of the Federal Statistical Office – the cap would only just bite. Its effect shows in periods of high inflation: the index-linked rent then loses part of its function as a hedge against inflation.
For valuation purposes a distinction must be made. In the general income approach, what counts is the income achievable in line with the market (Section 31(2) ImmoWertV), not the contractual clause. For contractually fixed income – in the periodic income approach under Section 30 ImmoWertV and in the DCF method – indexation, by contrast, feeds directly into the forecast. If inflation rises, the contract rent grows more slowly than the index, and a gap to the market rent can open up. Such an underrentA contract rent below the rent achievable in line with the market. In the appraisal report it is taken into account as a special income situation for as long as the contractual commitment lasts. is a special property-specific characteristic within the meaning of Section 8(3) sentence 2 no. 1 ImmoWertV and must be taken into account accordingly.
Short-term leases: six months at most
Accommodation let only for temporary use is exempt from large parts of tenant protection – including the rent cap (Section 549(2) no. 1 BGB). For the first time, the bill sets a time limit: the exemption only applies where there is a special temporary need and for no more than six months. If a longer need arises after the start of the tenancy, the lease can be extended to a total of eight months. Beyond that, the general protective provisions apply, including the rent cap.
For the valuation of furnished flats let for fixed terms, this means: income from “temporary living” only counts as gross income to the extent that the letting model is legally sound. Section 31(2) ImmoWertV refers to the income achievable in line with the market with proper management and permissible use. Anyone acquiring a property at a price calculated on short-term rents above the rent cap is, in case of doubt, paying for income that is not sustainable.
Grace-period payment: consequences for rent loss and receivables management
To date, a tenant can only invalidate an extraordinary termination for payment arrears by settling the arrears no later than two months after the eviction action has become pending (Section 569(3) no. 2 BGB). According to the case law of the Federal Court of Justice, an ordinary termination declared in the alternative at the same time remains unaffected. Under Section 573(4) BGB-E, ordinary termination for payment arrears is to be excluded if the landlord is paid before it is received; the grace period and the right to make up the payment apply accordingly, but only once per tenancy.
For the appraisal report this changes little: for residential use, the rent loss risk is usually applied at the model rate under Annex 3 ImmoWertV. The change matters in practice for the landlord's receivables management – dunning, termination strategy and the question of when an eviction action makes economic sense. In addition, the bill raises the threshold for the simplified procedure for rent increases after modernisation from €10,000 to €20,000 per flat (Section 559c(1) BGB-E).
What this means for rental value appraisals and market value
The market value of a let flat or an apartment building depends on the income a buyer can expect on a sustainable basis. Rent Law II shifts this income in three places:
- Rent assumptions: Asking rents for furnished flats are no evidence of the market rent. Anyone using them as comparison data must strip out the furniture surcharge. The fact that it will have to be shown separately in future makes this adjustment easier.
- Deviating contract rents: Excessive rents are not sustainable income; capped index-linked rents can fall behind the market. Both must be assessed as special income situations.
- Purchase prices: If a purchase price is based on the yield from furnishing or short-term letting, it must be checked which part of the income is still permissible under the new law.
A simplified model calculation for the example flat shows how much this matters: the difference of €5,976 in annual rent, less 2 per cent rent loss risk, capitalised over a remaining useful life of 40 years at a property yield of 2.5 per cent (present value factor 25.10), corresponds to around €147,000 of income value. Each euro of monthly rent in the income approach therefore counts roughly three hundred times. Owner-occupied flats are usually valued using the sales comparison approach; for investors who calculate on the basis of yield, however, the calculation shows what is at stake.
Rent increases during an existing tenancy
For increases to the local comparative rent, the bill does not change the procedure. The landlord can justify a request for a rent increase with, among other things, a rent index, three comparable flats or a reasoned report by a publicly appointed and sworn expert (Section 558a(2) BGB). Two recent decisions show what matters:
- Federal Court of Justice, order of 15 July 2025 – VIII ZB 69/24: The local comparative rent cannot be established in advance in independent evidentiary proceedings. It is an evaluative decision of the court in the consent proceedings, and the landlord bears the costs of substantiating the rent increase request.
- Regional Court of Itzehoe, judgment of 16 January 2026 – 9 S 21/25: A type report does not have to deliver a precise figure, but it must derive the rent range comprehensibly and link it to specific residential value features.
What landlords and buyers should check now
- Set up an inventory with purchase date, purchase price and receipt for every furnished flat.
- Show the furniture surcharge separately in the lease and disclose it before the contract is concluded.
- For index-linked rents, monitor whether the state issues an ordinance under Section 557b(4) BGB-E.
- For short-term leases, document the reason and limit the term.
- When acquiring a property, check the rent roll for permissible rather than achieved or advertised rents – and take the transitional rules for existing leases into account.
The new rules at a glance
| Rule | Provision in the bill | Content |
|---|---|---|
| Furniture surcharge | Section 556d(1a) BGB-E | no more than 1% of the current value per month; up to 10% of the unfurnished rent presumed reasonable for full furnishing |
| Duty to provide information | Section 556g(1b) BGB-E | disclose the surcharge before the contract is concluded, otherwise the flat is deemed let unfurnished |
| Index-linked rent | Section 557b(4) BGB-E | index increase above 3% a year counts only by half; only in designated areas |
| Short-term lease | Section 549(2) no. 1 BGB-E | no more than six months, extension to a total of eight months |
| Grace-period payment | Section 573(4) BGB-E | subsequent payment also prevents ordinary termination, once per tenancy |
| modernisation | Section 559c(1) BGB-E | simplified procedure up to €20,000 per flat |
Conclusion
Rent Law II is still a bill, but its direction is clear: what a flat may earn in rent is being tied more closely to verifiable figures – the current value of the furniture, the development of the index and the duration of the need. For rental value and market value appraisals, this means separating the permissible income cleanly from the income achieved or advertised and substantiating every surcharge. Anyone letting furnished or with an index-linked rent, or planning to acquire such a property, should have their leases and calculations reviewed now – legally and economically.
As of 8 October 2026. This article describes the government bill in the version of BT-Drs. 21/6807; changes in the parliamentary procedure are possible.
The full derivation of the local comparative rent, traceable for third parties, is provided by the Rental value appraisal.
Please note: the content of this article is provided for general information only and does not constitute legal, tax, financial or investment advice. It is not a substitute for individual advice from a licensed lawyer, tax adviser or financial adviser. Despite careful research, we accept no liability for the accuracy, completeness or currency of the information provided. For specific legal or tax questions, please consult a qualified professional adviser.